
Updated November 5, 2026.
Buyers usually weigh two numbers: the monthly payment and the cash they need to close. A price reduction can help, but it is not the only option. A well-chosen incentive, clearer property information or better presentation may address the specific concern holding a buyer back.
Redfin estimated that the U.S. had 62.6% more home sellers than buyers in September 2026, approximately 63%. That was the largest gap in its records, which begin in 2013. It is a national estimate, not a measure of every Orange County neighborhood. Local comparable sales and competing listings still matter.
Seller concessions are already common. In Redfin buyers’ agents’ reported transactions during the three months ending August 31, 2026, 44.7% included a seller concession. Another finding from that same sample: 15.8% included both a price reduction and a concession. Those figures describe a rolling three-month sample, not every August sale.
Here are five options to discuss before changing your asking price.
1. Help with closing costs
A buyer may be comfortable with the monthly payment but short of cash for closing. An eligible seller credit can reduce that upfront hurdle.
For context, NAR’s 2025 buyer profile reported a median 10% down payment among first-time buyers. That is a median, not a minimum requirement. The Federal Reserve’s 2022 Survey of Consumer Finances found a median transaction-account balance of $8,000 among families holding those accounts, measured in 2022 dollars. That figure is not specific to prospective homebuyers or the money they have available for a down payment.
Consider an illustration: a $450,000 home, 5% down, closing costs estimated at 3% of price, and a 30-year fixed loan at 6.95%. A $10,000 price cut would reduce estimated upfront cash by about $800 and principal-and-interest payments by about $63 a month. An allowable $10,000 closing-cost credit could instead reduce cash needed at closing by up to $10,000, without changing the loan’s payment.
The 6.95% rate is Freddie Mac’s national survey average from September 17, 2026, used only for this illustration. It is not a current rate quote. Freddie Mac’s November 5, 2026 survey reported a 7.18% 30-year average. Actual rates, closing costs, eligibility and allowable credits vary. A seller credit cannot be used for the buyer’s down payment, and unused credits may be limited.
Next step: Ask the buyer’s lender which costs a seller credit can cover and how much the loan program permits.
2. Explore a rate buydown
Some buyers are more concerned about the monthly payment. A lender can explain whether a temporary or permanent rate buydown would be useful for the loan they qualify for.
Realtor.com reported an average advertised builder incentive rate of 3.92% in August 2026 among listings offering reduced-rate incentives. These were promotional offers, often first-year rates through temporary buydowns or adjustable-rate loans. They were not universally available permanent fixed rates.
An individual seller should not assume they can match a builder’s offer. Compare the cost, duration, eligibility and later payment before presenting an incentive.
Next step: Get a written lender illustration before promising a rate or monthly payment.
3. Address condition questions before listing
Redfin reported that about 14% of home-purchase agreements fell through in July 2026, roughly one in seven. Its discussion identified several potential reasons, including inspection issues, appraisals, concession disagreements, financing changes, affordability and uncertainty. It did not establish what share was caused by inspections.
A pre-listing inspection may help you understand the property’s condition earlier. Depending on the findings, you might repair a problem, account for it in the price or disclose it to buyers. It is not a guarantee that a later inspection will find nothing new.
Next step: Discuss the cost, scope and disclosure implications with your agent before ordering an inspection.
4. Focus staging on the rooms buyers notice
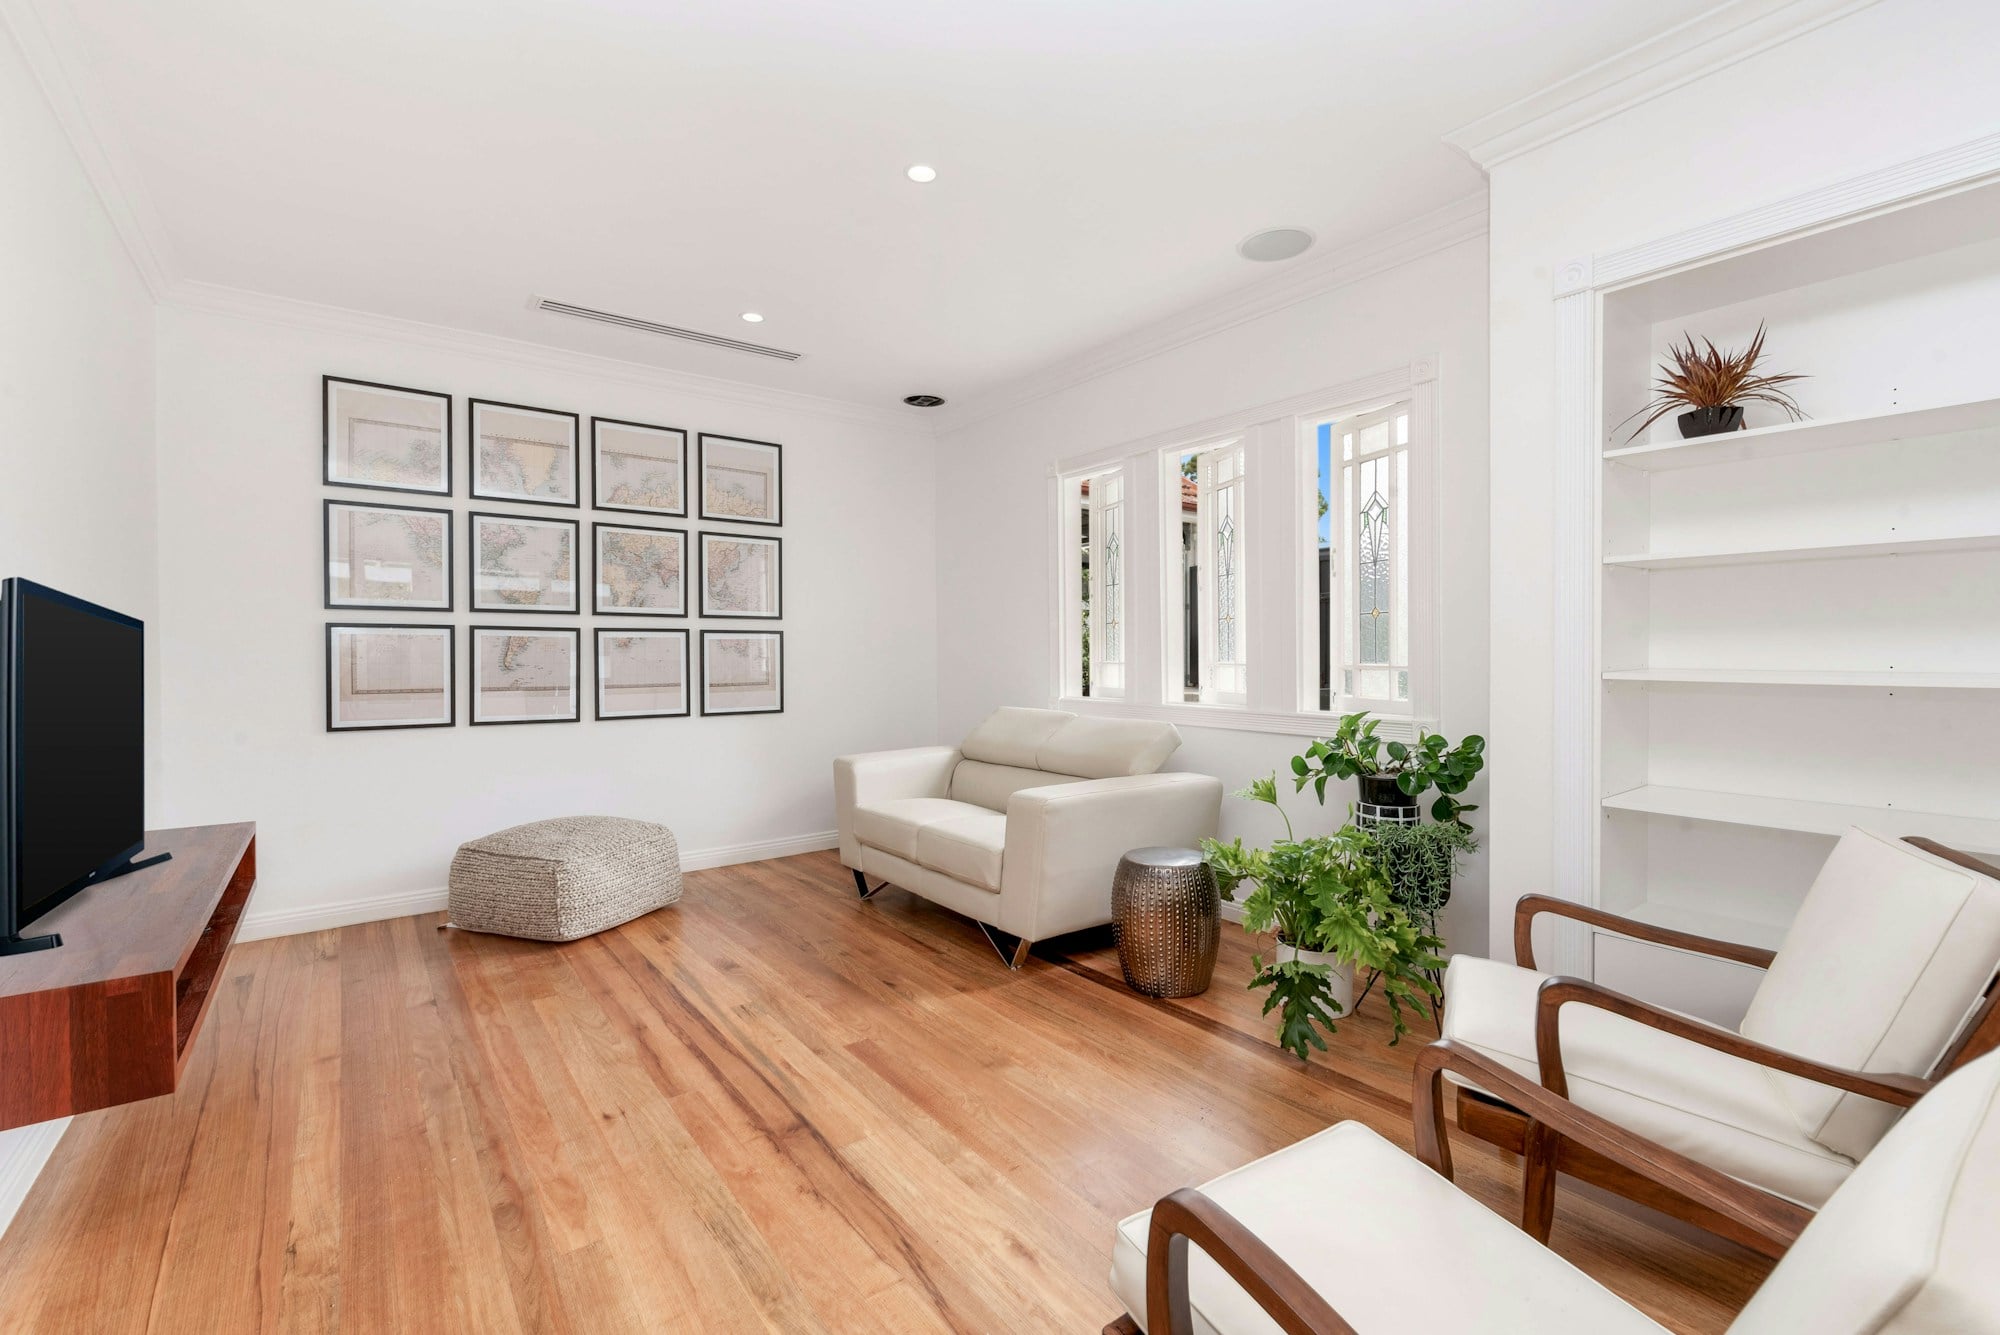
In NAR’s 2025 staging survey, 83% of buyers’ agents said staging helped buyers envision a property as their future home. The rooms most often ranked as important were the living room at 37%, primary bedroom at 34% and kitchen at 23%. These are survey opinions, not a promise of a higher sale price.
You may not need to stage every room. Clear surfaces, address small repairs, improve lighting and plan professional photography around the spaces that best show how the home lives.
Next step: Walk through those three rooms with your agent and choose the improvements most likely to help your particular home.
5. Let buyers choose an eligible incentive
If you are comfortable offering a fixed incentive budget, ask whether it can be structured around what the buyer needs: eligible closing costs, a lender-approved buydown or a different purchase price.
The same dollars cannot deliver every benefit at once. How an incentive is used must fit the loan program, appraisal and written purchase agreement. A credit that a buyer cannot use provides little help.
Next step: Compare the alternatives with your agent and the lender before including them in an offer or counteroffer.
Choose the option that addresses the real obstacle
Start with current comparable sales, the homes you are competing against and the feedback buyers are giving you. Sometimes the price needs to change. Sometimes cash to close, the payment, condition or presentation deserves attention first.
Want to discuss which options may fit your Orange County home? Call or text James Deokar at (949) 572-7098.
James Deokar | BK Platinum Properties
Examples are for illustration only, not a loan offer, rate quote, appraisal or promise of value. Payment illustrations include principal and interest only, excluding property taxes, insurance, mortgage insurance and HOA dues. Seller contributions, buydowns and other concessions are subject to lender and loan-program limits. Consult a licensed lender about available financing. If your home is already listed with another broker, this is not a solicitation.
Sources
- Redfin: September 2026 buyers versus sellers, published October 14, 2026.
- Redfin: concessions in the three months ending August 31, 2026, published September 18, 2026.
- Redfin: July 2026 contract cancellations, published August 21, updated August 27, 2026.
- Freddie Mac: September 17, 2026 mortgage-rate release.
- Freddie Mac PMMS archive, November 5, 2026 survey.
- Realtor.com: builder incentive-rate research, published September 15, 2026.
- NAR: 2025 Profile of Home Buyers and Sellers, published November 4, 2025; transactions July 2024 through June 2025.
- NAR: 2025 staging survey, published May 6, 2025.
- Federal Reserve: Changes in U.S. Family Finances from 2019 to 2022, published October 2023.
Check out this article next